Structural Scope of Proposed Taxonomy Refinements
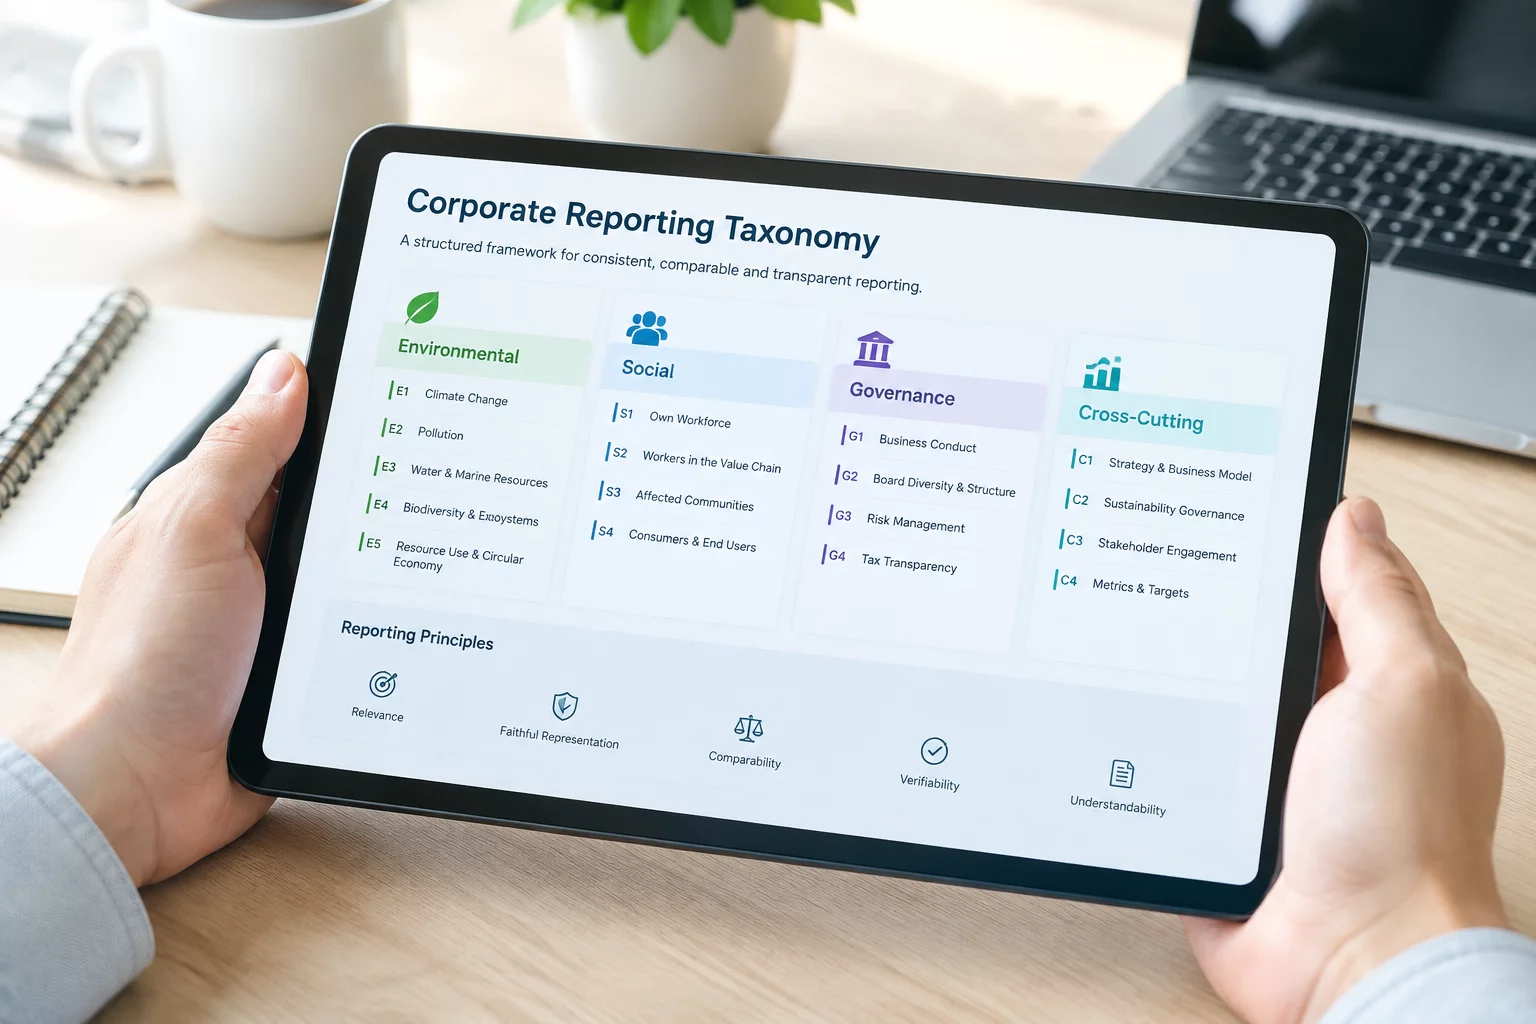
The Financial Accounting Standards Board has formally introduced an extensive package of technical improvements for the 2027 GAAP Financial Reporting Taxonomy. This release centers on streamlining standard tags, pruning redundant branch definitions, and addressing semantic inconsistencies that previously required custom extensions in corporate disclosures.
By consolidating parallel branches across various reporting schedules, the proposed framework enhances cross-entity comparability while substantially reducing validation warnings during automated intake passes. Technical teams can expect three primary architectural focus areas:
- Pruning of over 140 underutilized legacy line-item concepts and redundant abstract headers.
- Re-anchoring of hypercube dimensions to align disclosure tables directly with codification references.
- Clarification of calculation tree weightings to enforce logical balance check consistency.
"The 2027 technical architecture systematically reduces structural friction in data extraction pipelines, creating cleaner alignment between machine-readable tags and underlying accounting principles."
— Technical Taxonomy Oversight Group
Deprecation Schedules and Dimensional Mapping
A central objective of the 2027 cycle involves phasing out legacy elements that have caused recurring tagging ambiguities in corporate reporting. These modifications eliminate contradictory member designations, allowing analytical engines to parse structured disclosures with higher deterministic precision.
Organizations preparing automated validation rules must update data dictionaries to prevent pipeline exceptions when older element schemas transition to deprecated status during official regulatory filing periods.
Integration Strategies for Technical Data Pipelines
Transitioning enterprise reporting architectures toward the 2027 taxonomy draft necessitates structured cross-mapping exercises. Establishing automated syntax regression test suites allows corporate data engineering teams to benchmark existing custom extensions against the new core elements.
Early integration testing validates calculations across multi-period models, ensuring semantic continuity between prior historical disclosures and modern analytical visualization pipelines.